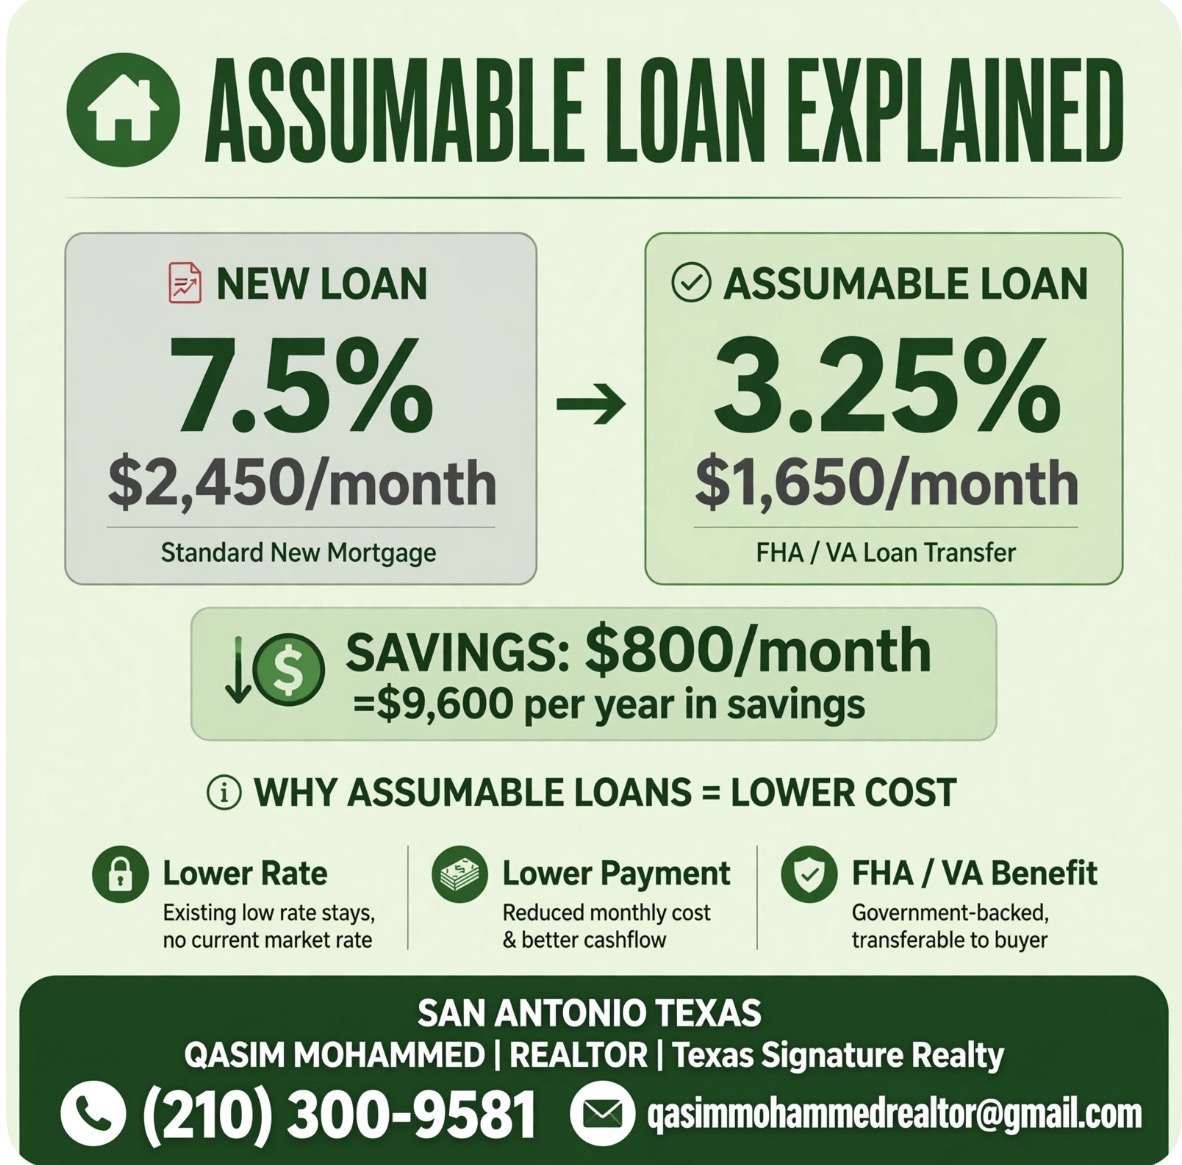
Steps to Buying a Property with an Assumable Loan
1. Understand Assumable Loans
- Assumable loans are typically government-backed loans, such as FHA, VA, or USDA loans. Conventional loans are rarely assumable.
- The buyer takes over the seller’s existing mortgage, including the interest rate and remaining term.
2. Identify a Property with an Assumable Loan
- Work with a real estate agent to find properties that have assumable loans.
- Check property listings and ask sellers directly if their mortgage is assumable.
3. Review the Loan Terms
- Obtain information about the current loan, including interest rate, remaining balance, and term.
- Ensure the terms are favorable compared to current market rates.
4. Assess Financial Suitability
- Ensure that you qualify for the loan based on your financial status.
- Conduct a cost-benefit analysis to decide if assuming the loan is beneficial.
5. Negotiate with the Seller
- Discuss the terms of the sale with the seller.
- Agree on a purchase price and any other conditions of the sale.
6. Apply for Loan Assumption
- Contact the lender to initiate the loan assumption process.
- Complete any necessary application forms and provide required documentation (e.g., proof of income, credit report).
7. Undergo Credit and Financial Review
- The lender will review your credit history and financial standing to determine your eligibility to assume the loan.
- Be prepared to provide additional documentation if requested by the lender.
8. Obtain Approval from the Lender
- Once the lender approves your application, they will provide a loan assumption agreement.
- Review the agreement carefully to ensure all terms match what was discussed.
9. Close the Sale
- Work with a title company or real estate attorney to finalize the transaction.
- Sign all necessary documents, including the loan assumption agreement and transfer of ownership documents.
10. Pay Closing Costs
- Be prepared to pay any closing costs associated with the assumption of the loan.
- These costs may include lender fees, title insurance, and other related expenses.
11. Transfer Ownership
- After closing, the title is officially transferred to you.
- Ensure all paperwork is properly filed and recorded with the appropriate local authorities.
Tips
- Consult Professionals: Work with a real estate agent and possibly a real estate attorney to navigate the complexities of an assumable loan.
- Verify Loan Terms: Double-check the loan terms to confirm they are advantageous compared to securing a new mortgage.
- Understand VA Loan Specifics: If assuming a VA loan, ensure the seller obtains a release of liability from the VA, if applicable.
For more personalized assistance or to explore properties with assumable loans, feel free to contact me:
Click Here
By following these steps and reaching out for guidance, you can effectively navigate the process of purchasing a property with an assumable loan.
Join My Blog
Seller's Success Hub is your ultimate resource for everything you need to know about selling your property. From preparing your home for the
market to negotiating the best deal, we provide expert tips, step-by-step guides, and insider advice to help
Subscribe