Sign In
Create an account and enjoy all the benefits of HAR.com!
Sign In
Sign in using social account


Texas homeowners are searching for home equity answers at a pace not seen in years. Google Trends data for Texas shows search interest in "HELOC" up about 29% over the past 12 months compared with the year before. "Home equity loan" is up about 32%, and "cash out refinance" about 60%. The fastest-rising questions aren't about rates. They're more basic: What is a HELOC, and how does it work? and What does a HELOC cost compared with a home equity loan?
Those are the right questions to start with, because in Texas the answer is different from what you'll read in most national articles. Texas has some of the strongest homeowner protections in the country, and they directly limit how much you can borrow against your home.
This guide covers the three main ways to access your equity, the Texas rule that caps all of them, and a worked example so you can estimate your own number.
The three options, in plain language
1. Home Equity Line of Credit (HELOC)
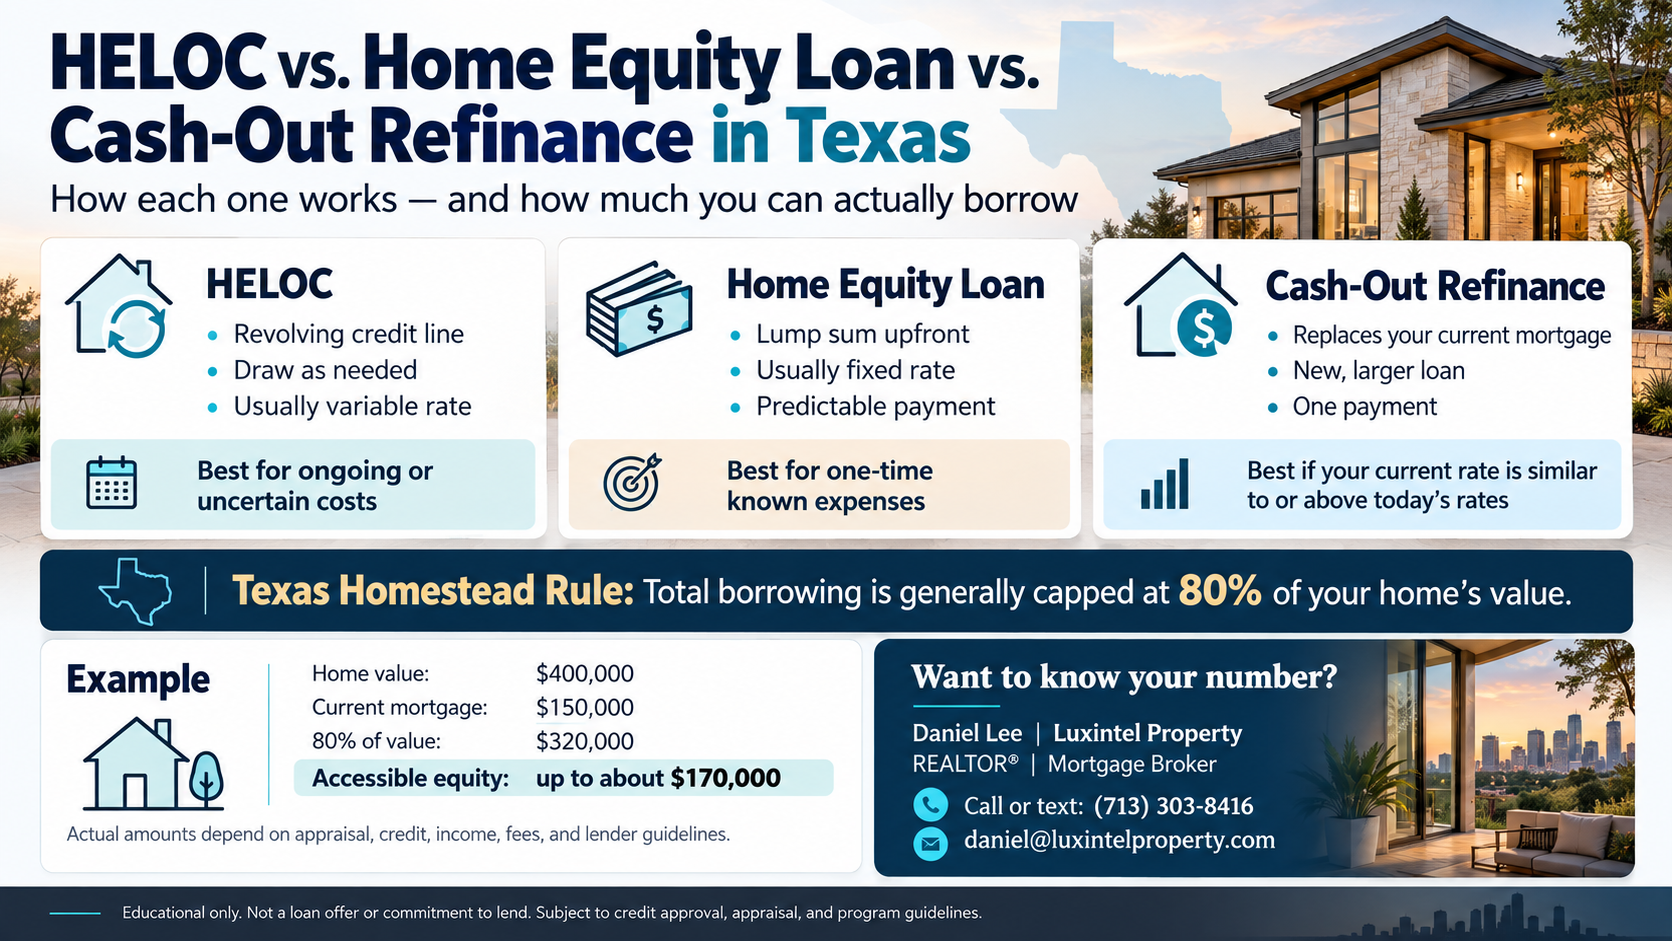
A HELOC works like a credit card secured by your home. You're approved for a maximum amount, draw from it as you need it, and pay interest only on what you've used. Most HELOCs have a variable rate, so your cost can rise or fall over time.
Best for: ongoing or uncertain expenses, like a renovation paid in stages or a safety net you may never touch.
2. Home Equity Loan
A home equity loan gives you one lump sum up front, usually at a fixed rate, repaid over a set term. Your existing first mortgage stays exactly as it is.
Best for: one-time expenses with a known cost, like a roof replacement or paying off high-interest debt, when you want a predictable payment.
3. Cash-Out Refinance
A cash-out refinance replaces your current mortgage with a new, larger one. You receive the difference in cash. You end up with one loan and one payment, but your entire mortgage balance moves to a new rate and term.
Best for: homeowners whose current mortgage rate is similar to or higher than today's rates, or who want to combine everything into a single loan.
The Texas rule that changes the math: the 80% cap
In Texas, loans that let you take cash out of your homestead are generally limited to 80% of your home's value, including all loans against it. That covers home equity loans, HELOCs, and cash-out refinances. The limit comes from the Texas Constitution, and it applies no matter how strong your credit or income is.
Texas also adds other consumer protections to home equity lending, including required waiting periods and a right to cancel after closing. They're good for homeowners, but they mean Texas equity loans take more planning than they would in many other states.
One distinction to know: these homestead rules apply to the home you live in. Investment properties follow different lending guidelines.
A worked example: how much could you access?
Say your Houston-area home is worth $400,000 and you owe $150,000 on your mortgage.
Here's how each option would use that room:
Your actual amount depends on a professional appraisal, your credit, your income, and the lender's guidelines. But the 80% cap is the ceiling everyone starts from.
HELOC vs. home equity loan: what does each one actually cost?
This is one of the fastest-growing searches in Texas, and the honest answer is that it depends on how you'll use the money.
How to choose
Why comparing lenders matters
Rates, fees, and approval guidelines for equity products vary a lot from one lender to the next, and many homeowners simply take whatever their current bank offers. Checking several lenders before you commit is one of the easiest ways to lower what you pay.
As a dual-licensed REALTOR® and mortgage broker, I compare options across multiple lenders, and I can tell you what your home is worth in today's market before you apply. That way you know your real equity number instead of guessing.
Find out your number
If you're curious how much equity you could access, I'll prepare a free, no-obligation home value analysis for your property.
Daniel Lee
Founder & Principal Strategist, Luxintel Property
REALTOR® Mortgage Broker
Call or text: (713) 303-8416
daniel@luxintelproperty.com
Related reading from Luxintel Property:
Methodology: Search trends reflect Google Trends relative search interest for Texas, comparing the most recent 12 months with the prior 12 months. Google Trends measures relative interest, not absolute search volume. This article is educational and is not a loan offer or commitment to lend. All loans are subject to credit approval, appraisal, and program guidelines.
Daniel Lee Luxintel Property TREC License #838122 NMLS #2714789 Callis & Co Realty Straight Arrow Mortgage


 Erase note
 You currently have no custom folders