Sign In
Create an account and enjoy all the benefits of HAR.com!
Sign In
Sign in using social account


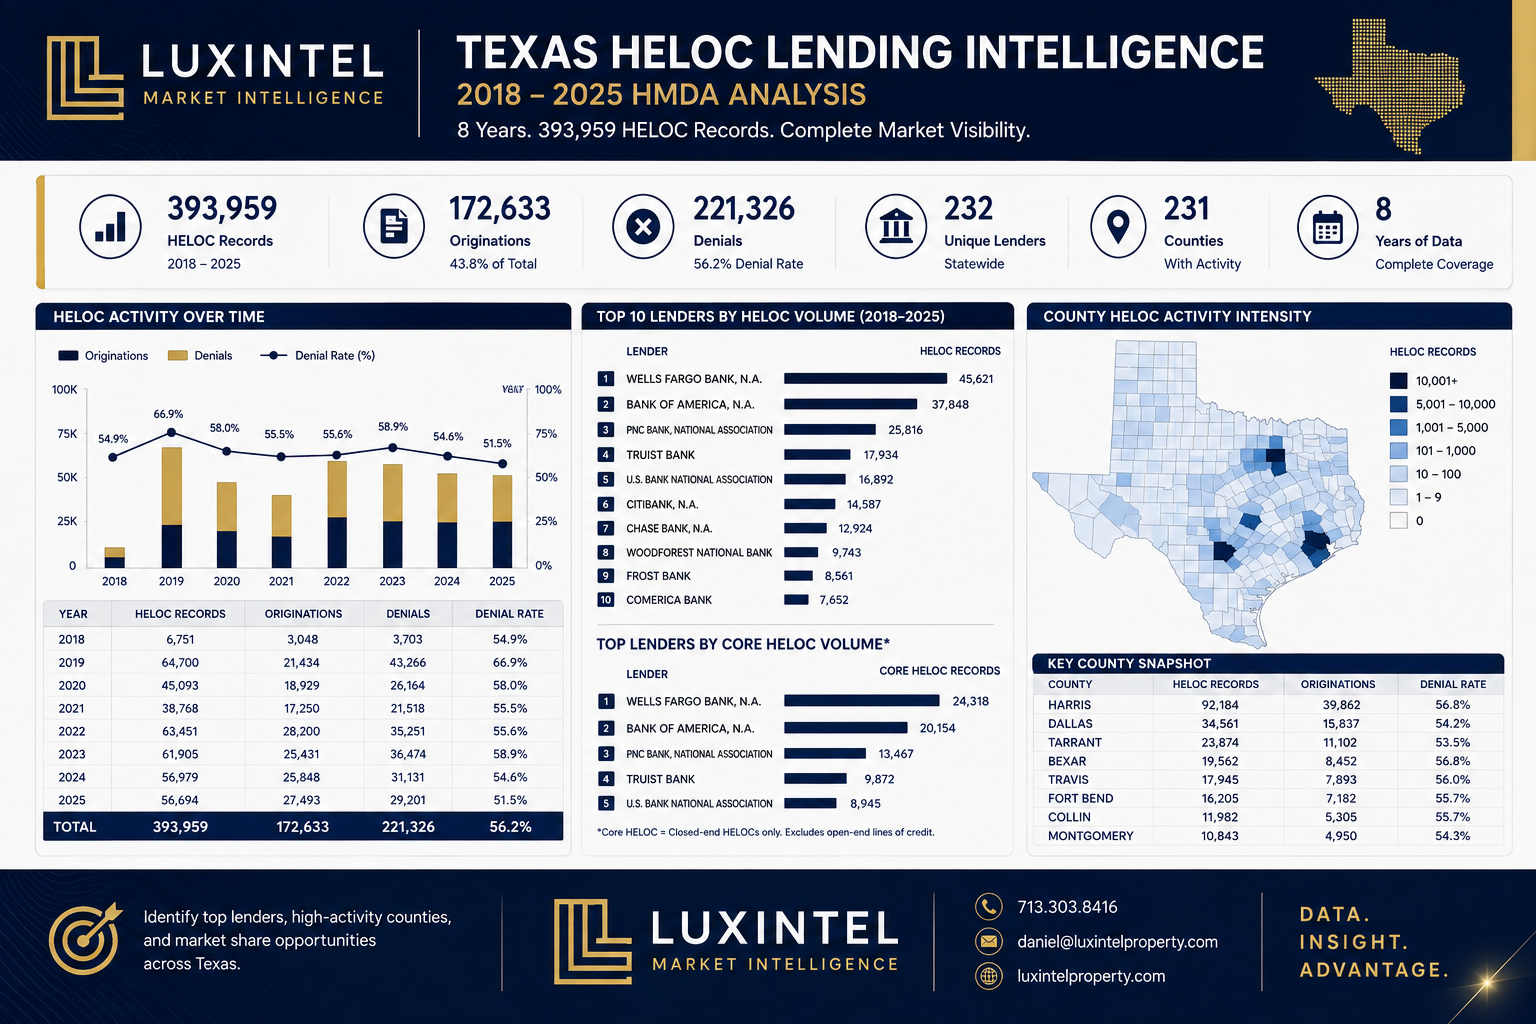
Home equity lines of credit have quietly become one of the most active corners of the Houston mortgage market this year, and the newest federal lending data gives us a clear picture of who's actually writing these loans — and how differently they're treating applicants.
Across the Houston metro, five lenders account for a disproportionate share of HELOC originations: Bank of America, Zions Bancorporation, PNC Bank, Frost Bank, and a handful of regional credit unions and fintech lenders that have grown fast in the last year. But market share alone doesn't tell you which lender is right for your situation — the denial-rate data does.
The gap between lenders is bigger than most homeowners realize
Some Texas HELOC lenders are approving well over half of the applications they receive. Others are denying more than two-thirds. That's not a small difference — it means the lender you happen to walk into matters as much as your credit profile does. A borrower who gets turned down at one bank may be a strong candidate at another, simply because that lender's underwriting box is wider or its typical borrower profile is different.
This is exactly why shopping a HELOC the way you'd shop a purchase mortgage — getting more than one quote, comparing terms, and not assuming your everyday bank is the most competitive option — tends to pay off. A lot of homeowners default to whoever holds their checking account, and that's often not the lender best positioned to say yes.
Houston-area counties are seeing different dynamics
Harris, Fort Bend, and Montgomery counties remain the highest-volume markets for home equity lending in the region, but the competitive picture looks different county by county. In Galveston and Brazoria counties, a regional credit union has emerged as the top originator rather than a national bank — a reminder that the "biggest name" isn't always the biggest lender in your specific zip code.
Meanwhile, several non-bank and fintech lenders have posted triple-digit growth in originations over the past year, expanding rapidly into markets that used to be dominated almost entirely by traditional banks. For homeowners, that growth means more competition for your business — and more room to negotiate rate, fees, and line size than there was even twelve months ago.
What this means if you're considering tapping your equity
If you're weighing a HELOC to fund a renovation, consolidate debt, or free up cash for another purchase, a few things are worth keeping in mind:
Property values across most Houston-area counties remain high enough that many homeowners are sitting on more usable equity than they realize, even after a few years of a slower resale market.
Denial rates vary enormously by lender — a decline from one institution is not a verdict on your overall creditworthiness.
Credit unions and regional banks are increasingly competitive with the national names, particularly outside the core Harris County market.
The lending landscape is shifting quickly enough that a lender's product from a year ago may not reflect what they're offering today.
If you're thinking through whether a HELOC, a cash-out refinance, or a different equity strategy makes the most sense for your goals, I'm happy to walk through the numbers with you and help you understand where you'd likely land with different lenders before you apply anywhere.
Daniel Lee is a dual-licensed Texas real estate agent (TREC #838122) and mortgage loan originator (NMLS #2714789) with Callis & Co Realty and Straight Arrow Mortgage.


 Erase note
 You currently have no custom folders