Sign In
Create an account and enjoy all the benefits of HAR.com!
Sign In
Sign in using social account


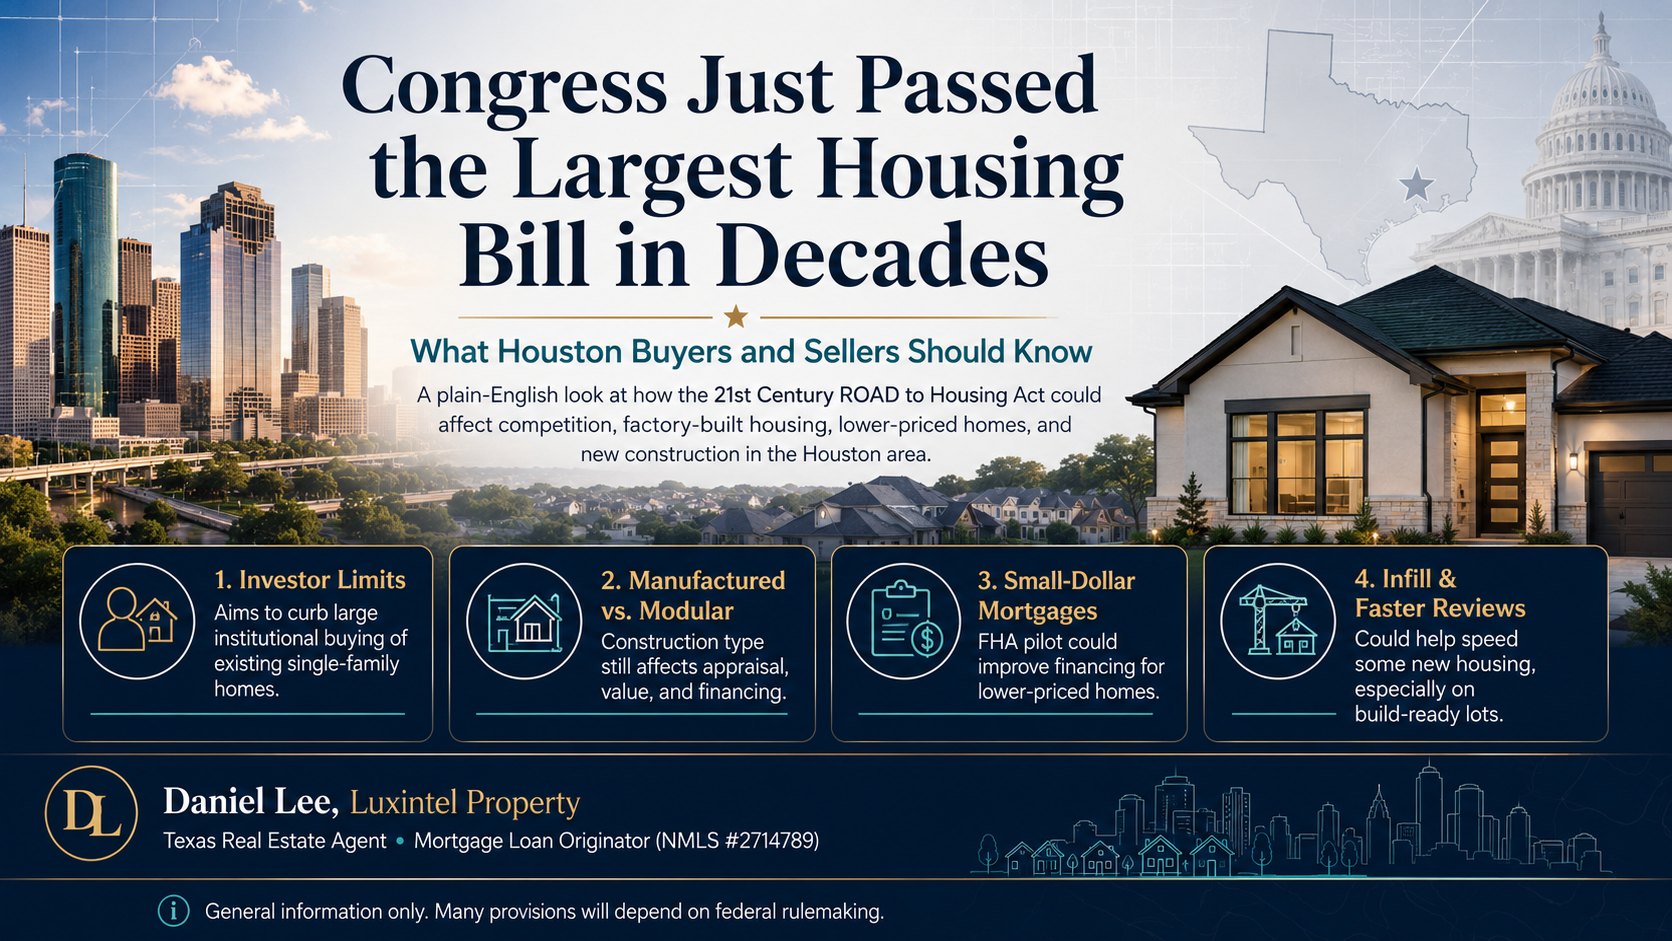
Congress has passed the 21st Century ROAD to Housing Act (H.R. 6644), a wide-ranging federal housing package and the most significant housing legislation in more than three decades. The House approved it 358-32 on Tuesday, a day after the Senate cleared it 85-5, and it now heads to the President's desk, where it is expected to be signed into law.
For Houston-area buyers, sellers, and homeowners, the bill is worth understanding because it touches several things people ask me about constantly: who gets to compete for homes, how newer types of homes are valued and financed, how lower-priced homes get funded, and how quickly new housing can be built. Here is a plain-English look at the parts most likely to affect everyday transactions across Harris and Brazoria counties.
The provision drawing the most national attention is titled "Homes Are For People, Not Corporations." It restricts large institutional investors from purchasing single-family homes, with the goal of preserving more inventory for individuals and families.
The detail that matters: this targets large operators, not ordinary buyers, landlords, or small investors. The restriction applies to entities that control roughly 350 or more single-family homes. It also carves out newly constructed homes and build-to-rent communities, so it is aimed at the large-scale purchase of existing houses rather than at new construction. In fast-growing Sun Belt metros like Houston, where institutional buyers have been active in many neighborhoods, this could ease some of the competition individual buyers have faced for existing starter and mid-priced homes. How much it changes day-to-day bidding will depend on how it is implemented and enforced.
One of the most discussed provisions updates the federal definition of a manufactured home so that these homes can be built with or without a permanent steel chassis. In practical terms, that allows factory-built homes to look and sit on a foundation more like a traditional home.
Here is the part buyers and sellers should not misread: removing the chassis does not automatically make a manufactured home appraise like a site-built home. A home's appraisal category is driven by its HUD certification label and data plate, which mark how the home was originally constructed. A home built to the federal HUD code is generally appraised against other manufactured homes, while a modular home built to the same state and local building codes as a site-built home is appraised against site-built comparables.
There is already a pathway, separate from this bill, where certain higher-specification manufactured homes can be appraised more like site-built homes and financed with conventional loans. Those programs require specific design features and a special label. This new law makes it easier and cheaper for manufacturers to build toward those standards, which over time may bring more options into the market. If you are comparing a factory-built home to a traditional one, the construction type still matters for both value and financing, and it is worth confirming early rather than after you are under contract.
The bill authorizes a Federal Housing Administration pilot program aimed at small-dollar mortgages. If implemented, it could include direct help for qualified buyers with costs such as down payments, closing costs, appraisals, and title insurance, along with steps to encourage more lenders to make these smaller loans.
Smaller mortgages have historically been harder to find because the fixed costs of originating a loan do not shrink with the loan amount. For buyers shopping at the more affordable end of the Houston market, a program that lowers those entry costs could matter. The details would be set by federal rulemaking over the coming months, so this is one to watch as it takes shape.
Several provisions are designed to speed up new construction. One removes a layer of environmental review for certain federally assisted housing built on infill sites, meaning lots already served by existing water, sewer, and roads in built-up areas. The aim is to get attainable homes built faster on land that is already connected to infrastructure.
There is an important limit worth noting for our region: the streamlined treatment specifically excludes sites in areas designated higher risk for flooding under the Federal Emergency Management Agency's National Risk Index. In a coastal metro like Houston, that carve-out means the fastest-track benefits will tend to favor higher, well-drained lots over flood-prone parcels. Flood zone and elevation remain central questions for any new build here, just as they always have been.
Most of these changes roll out over the coming months as federal agencies write the rules, so the immediate effect on your transaction is limited. A few takeaways that hold regardless:
If you have been competing with large investors for existing homes, the new limits may gradually shift some of that pressure, especially in neighborhoods where institutional buyers have been active.
If you are considering a factory-built home, ask whether it is a HUD-code manufactured home or a modular home built to local building codes, because the answer affects appraisal and loan options.
If you are shopping at a lower price point, keep an eye on the FHA small-dollar pilot as details emerge, since it could reduce upfront costs for qualified buyers.
If you are looking at new construction on a vacant lot, confirm the flood zone and elevation early, as those drive both buildability and long-term cost.
I follow housing legislation closely because it shapes the numbers behind real decisions. As both a licensed Texas real estate agent and a licensed mortgage loan originator, I am glad to walk through how any of this applies to a specific property or situation, whether you are buying, selling, or just trying to make sense of your options.
This article is for general information only and is not financial, legal, or tax advice. The 21st Century ROAD to Housing Act was awaiting the President's signature as of writing, and many of its provisions will be phased in through federal rulemaking, so timing and final details may vary. For guidance on your specific situation, consult the appropriate licensed professional.
Daniel Lee, Luxintel Property. Texas real estate agent and mortgage loan originator (NMLS #2714789).


 Erase note
 You currently have no custom folders