Sign In
Create an account and enjoy all the benefits of HAR.com!
Sign In
Sign in using social account


About 1 in 4 existing home sales nationwide closed with cash in July. NAR reported cash deals made up 26% of transactions, compared with 31% a year earlier.
Cash is still a big part of the market. It's just a smaller part than it was last summer.
If you're buying with cash: You don't have financing approval hanging over the deal, and you may be able to close faster. That's leverage. Use it when negotiating price and terms, not just to beat another offer.
If you're selling to a cash buyer: There's less financing risk, but certainty sometimes comes with a lower offer. Compare what you actually walk away with, not just the number at the top of the contract.
Mortgage rates have stayed high, and forecasts have moved around throughout the year.
That's the problem with waiting for a forecast to save your payment. Nobody controls where rates go next.
What has changed is the amount of negotiating going on. Redfin reported that sellers gave buyers a concession in 58.5% of Houston area sales handled by its buyers' agents during the three months ending in August. Nationally, the figure was 44.7%.
That can mean money toward closing costs, repairs or a rate buydown.
If you're buying: Don't focus only on the sales price. A rate buydown can lower your monthly payment. A closing cost credit can reduce the cash you need at closing. Figure out which one actually helps you more before you negotiate.
If you're selling: Be prepared for buyers to ask for help. Sometimes a targeted credit gets a deal done without a larger price reduction.
About two thirds of outstanding mortgages still carry a rate under 5%, according to FHFA. That's one reason some owners aren't eager to sell a perfectly good house and trade a low rate for a much higher one.
But a low mortgage rate shouldn't automatically decide whether you move.
If you're thinking about selling: Run the numbers first. How much equity do you have? What would that equity buy? What would the new payment actually be?
Sometimes staying put makes sense. Sometimes the numbers are closer than you expected.
If you have an FHA or VA loan, there's another thing worth checking. Those loans are generally assumable with lender approval, so a qualified buyer may be able to take over your existing mortgage and its interest rate. VA borrowers should also understand how an assumption could affect their VA entitlement before agreeing to one.
This is the part of the market I watch especially closely.
At the end of July, the Census Bureau reported enough new homes for sale nationally to represent about 9.6 months of supply at the current sales pace.
That's a lot of inventory for builders to carry. When builders need to move houses, they have tools an individual homeowner usually doesn't have: rate buydowns, closing cost assistance, upgrades and sometimes price reductions.
I spent 23 years in the homebuilding supply chain before I ever got my real estate license. When I see a builder advertising a bought down mortgage rate, I want to know exactly how the deal is structured and what conditions come with it.
If you're buying new: Bring your own agent. Get the entire incentive package in writing. Ask whether the incentive requires using the builder's lender or title company. Ask what's included in the house and what counts as an upgrade. Then compare the total deal, not just the mortgage rate printed on the sign.
If you're selling a resale home nearby: The builder down the road may be your toughest competition.
You probably can't match a builder's financing incentives dollar for dollar. You don't necessarily have to.
You have a finished house. A finished yard. Mature landscaping. Window coverings. Improvements that may already be done. An established street and neighborhood. Buyers can see exactly what they're getting.
Those things have value too.
Greater Houston had about 5.3 months of single family housing inventory in August.
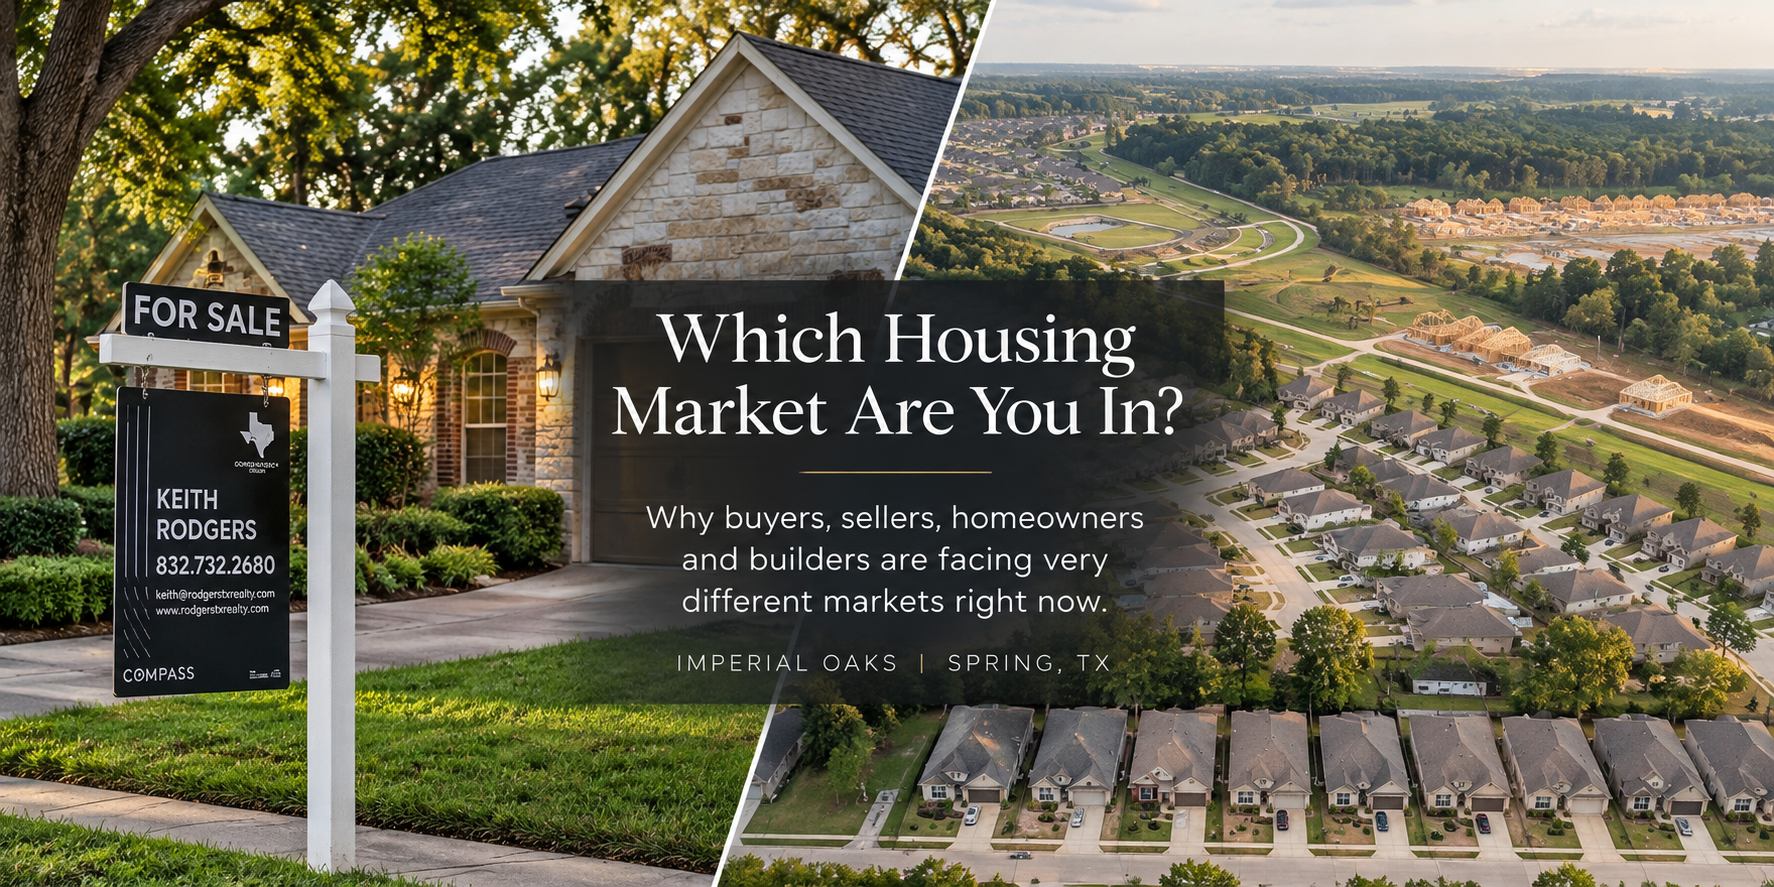
But our part of Spring shows why a metro wide number doesn't tell the whole story. The Falls and the Meadows share the Imperial Oaks name, but right now they're behaving like two different markets.
I pulled the HAR MLS numbers on September 21.
Since August 1, 11 homes have closed in the Falls. The median sale price was $410,000, or about $162 per square foot. On average, those sellers received about 97.6% of their original asking price, and the typical home sold in about 63 days.
Eight more homes were under contract, and 21 were active.
The active listings are beginning to split into two groups. Homes priced close to what recent sales support are getting attention. Meanwhile, eight of the 21 active homes had been on the market 130 days or longer, and seven had already reduced their price.
The Falls isn't soft. It's picky.
Buyers are there, but they're paying attention to price, condition and value.
The Meadows is a different market.
As of September 23, the builder had at least 35 new homes available and another 15 under contract. Some asking prices have been reduced, including several by roughly $30,000 to $43,000. Other homes have moved in the opposite direction.
And the advertised price doesn't always tell you the entire story. Builder rate buydowns, closing cost assistance and other incentives may not show up in the MLS price.
That's what makes this especially challenging for resale sellers. There are roughly two dozen resale homes currently listed in the Meadows, and they're competing with brand new houses only a few streets away.
The four resale homes that closed since early August sold for about 93% to 97% of their original asking prices.
If you own in the Meadows and you're thinking about selling, you're not just competing with your neighbor.
You're competing with the builder's model home.
Price with that in mind.
Then show buyers what the builder can't necessarily offer: a finished yard, completed improvements, an established location and a home that's ready now instead of depending on a construction schedule.
That's usually where I start when someone asks me how the market is.
Are you buying with cash? Financing? Sitting on a low mortgage rate? Selling against new construction? Selling in an established neighborhood where buyers are picky about price?
Those aren't the same market.
We look at your numbers, your timeline and what's actually selling around your house. A national headline can't do that.
Then you decide what makes sense.
Keith Rodgers, REALTOR®
Compass RE Texas, LLC
832 732 2680
Sources: National Association of REALTORS® Existing Home Sales, July 2026; Redfin seller concessions report, August 2026; U.S. Census Bureau New Residential Sales, July 2026; Federal Housing Finance Agency National Mortgage Database, Q1 2026; Houston Association of REALTORS® August 2026 housing data; HAR MLS data for the Falls at Imperial Oaks and the Meadows at Imperial Oaks, pulled September 21 and September 23, 2026.



 Erase note
 You currently have no custom folders