Sign In
Create an account and enjoy all the benefits of HAR.com!
Sign In
Sign in using social account


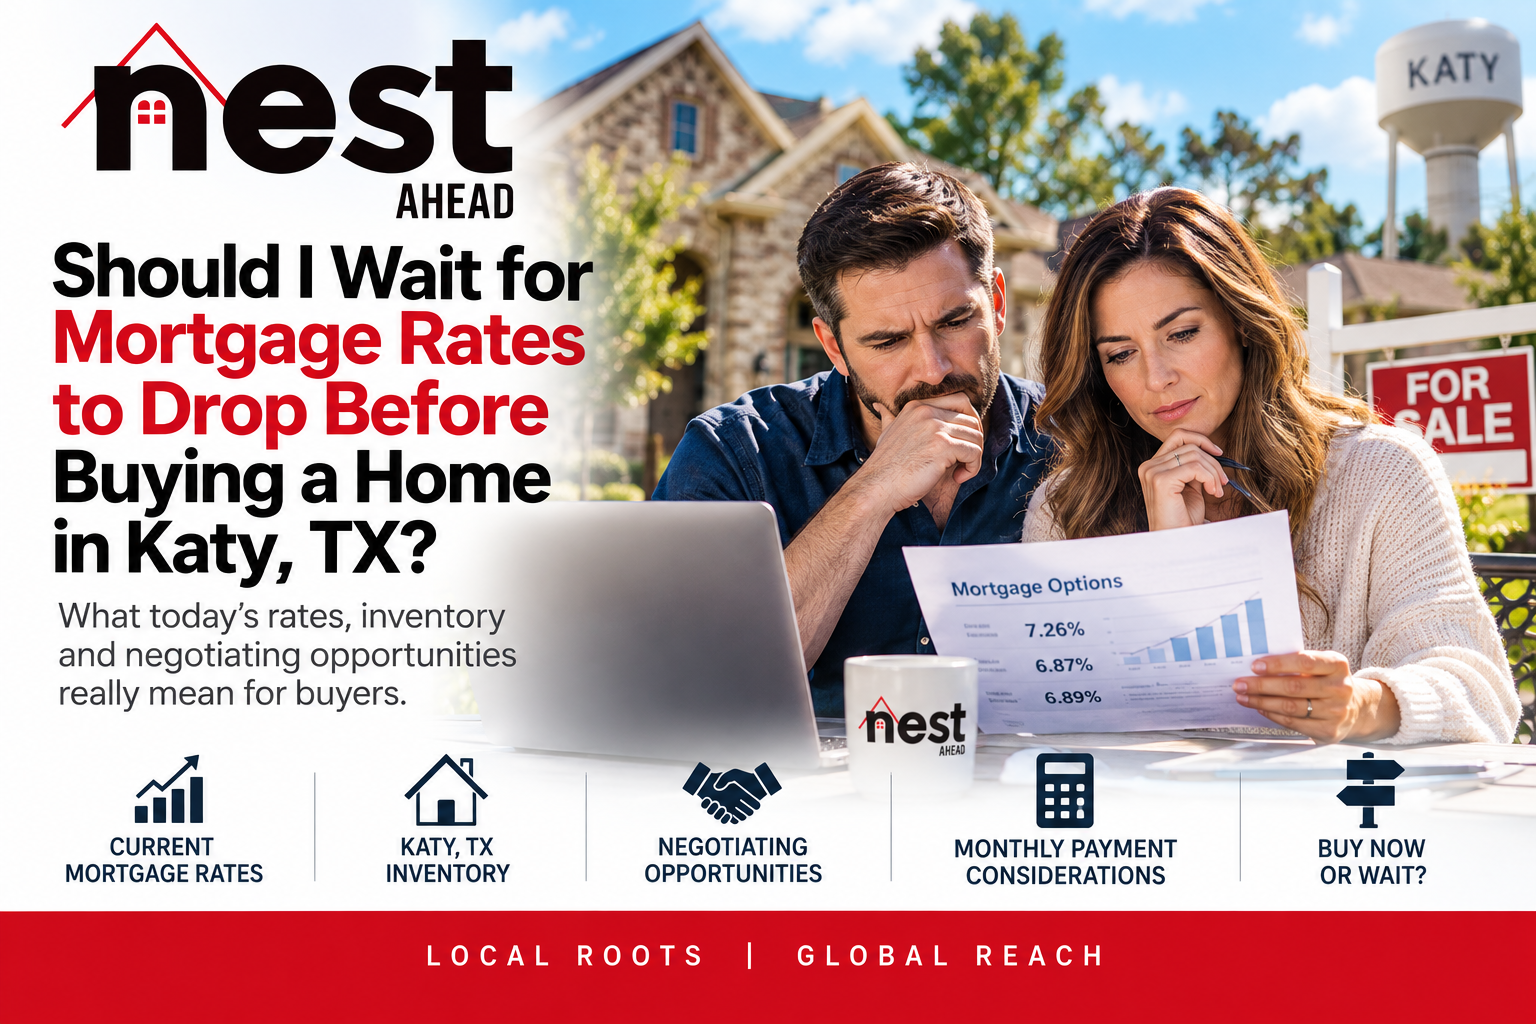
If you're considering buying a home in Katy, TX, should you put your plans on hold until mortgage rates come down?
It's one of the most understandable questions buyers are asking right now.
Mortgage News Daily reported its average 30-year fixed mortgage rate at 7.26% on September 23, 2026.
At that level, mortgage rates can have a significant effect on a buyer's estimated monthly principal-and-interest payment.
But I don't believe the answer is automatically:
“Wait.”
And I don't believe the answer is automatically:
“Buy now.”
The better question is whether purchasing a particular home makes sense using the financing, budget and Katy market conditions that actually exist today.
No one can reliably tell a buyer exactly where mortgage rates will be several months from now.
Rates could decline.
They could increase.
Or they could remain within a relatively narrow range for some time.
That's why I would be cautious about making a major housing decision based solely on someone's mortgage-rate prediction.
If today's payment does not work for your budget, waiting may absolutely be the right decision.
But that's different from waiting because someone has promised you a specific lower rate is coming.
Not necessarily.
A lower mortgage rate could improve affordability if everything else stayed exactly the same.
But the housing market may change too.
If lower rates eventually bring additional buyers into the market, competition for some homes could increase.
Inventory, home prices, builder incentives and seller negotiating leverage can also change.
That isn't a prediction that any of those things will happen.
It's simply why I don't think a buyer should evaluate the decision using the mortgage rate alone.
This is especially important locally.
A Katy mailing address can cover a very large geographic area, and market conditions aren't identical throughout it.
Inventory and competition can differ by:
A buyer considering one neighborhood could have meaningful negotiating leverage while another buyer several miles away could be looking at a home receiving substantially more interest.
That's why national housing headlines aren't enough to evaluate an individual Katy property.
Sometimes.
Depending on the property, seller and market conditions, a buyer might negotiate around items such as:
But negotiating leverage should never be assumed.
A well-priced property in excellent condition may attract significant interest even when the broader market gives buyers more choices.
Every property needs to be evaluated individually.
Potentially.
Depending on the loan program, lender requirements and negotiated contract, eligible seller contributions may sometimes be used toward certain buyer closing or financing costs.
For example, the buyer's lender may be able to explain whether discount points or a temporary buydown structure is available and how each option would affect the buyer.
That is why I like having the lender involved before deciding how to structure a financing-related request.
I am a REALTOR®, not a mortgage lender.
The lender determines what is permitted under the buyer's financing and provides the actual payment calculations.
I would not base today's home purchase on the assumption that a future refinance will occur.
Mortgage rates may eventually decline enough that refinancing becomes beneficial.
If that happens and the homeowner qualifies, great.
But refinancing is another mortgage transaction and can involve costs and qualification requirements.
A future refinance should be viewed as a potential opportunity, not something required to make today's purchase affordable.
Instead of trying to predict mortgage rates, I would start with information we can actually evaluate.
Ask your lender about:
Then evaluate the real estate itself.
I want to know:
Maybe.
If today's estimated payment does not fit comfortably within your plans, waiting can be a perfectly reasonable decision.
If you're not financially ready, waiting may also make sense.
But if the financing works, you find a home that meets your needs and the current market creates an attractive opportunity, I wouldn't automatically reject that opportunity solely because you're hoping mortgage rates will be lower later.
The goal isn't to perfectly time the mortgage market.
The goal is to make a housing decision that works for you using information you can actually verify.
If you're trying to decide whether buying now makes sense, I can help you evaluate the real estate side of the decision.
We can look at the homes currently available, comparable sales, neighborhood-level conditions, new-construction competition and potential negotiating opportunities.
Your lender can then provide the financing information specific to you.
Together, those numbers give you a much stronger basis for deciding whether to buy or wait than trying to guess where mortgage rates will be next.
Jonathan McNabb, REALTOR®
Broker/Owner, Nest Ahead
Katy, TX and Greater Houston
281-549-8099
Jonathan.NestAhead.com
Local Roots Global Reach
I am a REALTOR®, not a mortgage lender. This article is for general real estate education and is not mortgage, lending, legal, tax or financial advice. Mortgage rates and market conditions can change. Buyers should obtain financing information specific to their circumstances from an appropriately qualified mortgage professional and independently verify property-specific information before purchasing.



 Erase note
 You currently have no custom folders