Sign In
Create an account and enjoy all the benefits of HAR.com!
Sign In
Sign in using social account


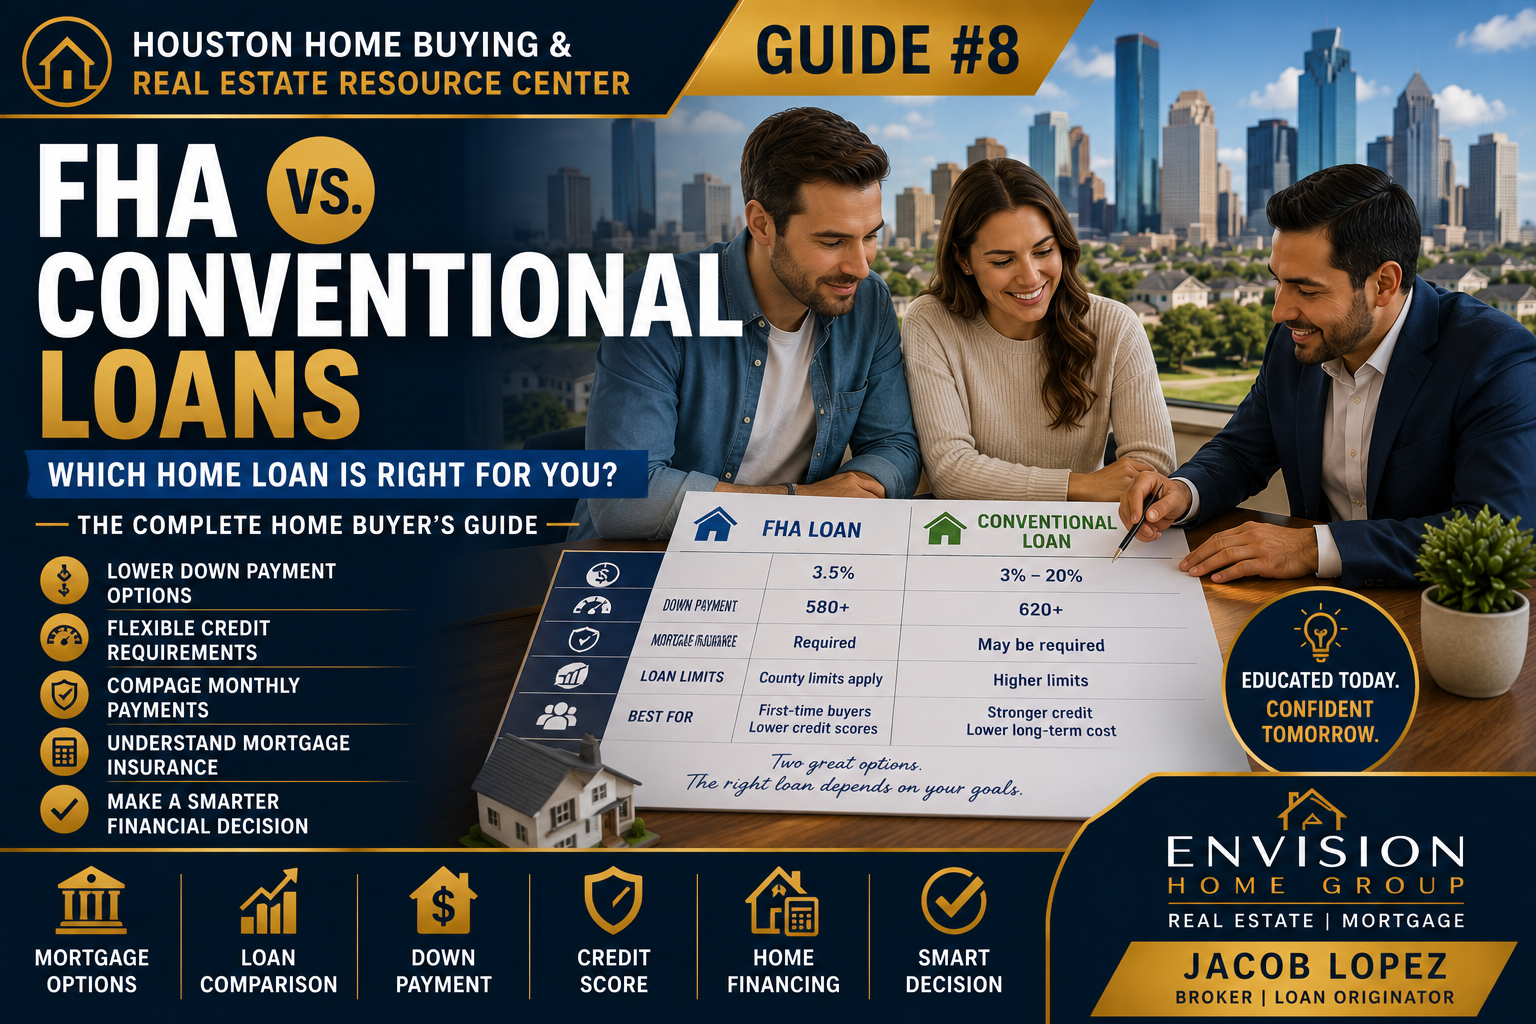
One of the first questions many buyers ask is:
"Which loan is better FHA or Conventional?"
The truth is, there isn't a universal answer.
The best loan isn't simply the one with the lowest interest rate or smallest down payment. It's the one that best supports your financial goals, monthly budget, and long-term plans.
I've worked with buyers who were convinced they needed an FHA loan, only to discover they qualified for a Conventional loan with a lower overall cost. I've also helped buyers who assumed they needed 20% down when they were able to purchase much sooner with significantly less.
The goal isn't choosing the "best" loan.
It's choosing the right loan for you.
FHA and Conventional loans are both excellent financing options, but they're designed for different situations.
In general:
FHA Loans may be a good fit for buyers who:
Have a smaller down payment.
Are building or rebuilding their credit.
Want flexible qualifying guidelines.
Are purchasing a primary residence.
Conventional Loans may be a good fit for buyers who:
Have stronger credit.
Want greater flexibility over the long term.
Can meet conventional qualification requirements.
Are looking to minimize certain long-term borrowing costs.
The best way to determine which option fits your situation is to compare both side by side before making a decision.
One of the biggest mistakes I see buyers make is assuming there is only one financing option available to them.
Many people search online, hear advice from friends, or read outdated information that doesn't apply to their situation.
That's why I like to compare multiple financing scenarios before anyone starts shopping for homes.
Sometimes the difference in monthly payment is smaller than expected.
Sometimes a different loan program helps preserve more savings after closing.
Sometimes one option creates greater flexibility for future financial goals.
Understanding your options early makes the rest of the home-buying process much easier.
FHA loans are government-insured mortgages designed to help make homeownership more accessible for qualified buyers.
Some potential advantages include:
Lower minimum down payment requirements for qualified borrowers.
Flexible credit guidelines.
Competitive financing options.
Popular with many first-time home buyers.
Potential considerations:
Mortgage insurance requirements.
Property must meet FHA appraisal standards.
Designed primarily for owner-occupied homes.
Conventional loans are not insured by the federal government.
They often provide additional flexibility for buyers who meet qualification requirements.
Potential advantages include:
Multiple down payment options.
Greater flexibility in certain situations.
Opportunity to eliminate private mortgage insurance (PMI) once eligible under applicable loan terms.
Suitable for a wide variety of buyers.
Potential considerations:
Credit and qualification standards may differ from FHA financing.
Down payment and reserve requirements vary depending on the loan scenario.
| Feature | FHA | Conventional |
|---|---|---|
| Down Payment | Lower minimum for qualified buyers | Multiple options available |
| Credit Flexibility | Generally more flexible | Depends on borrower profile |
| Mortgage Insurance | Required under FHA rules | May be required depending on loan-to-value ratio |
| Property Standards | FHA appraisal requirements | Conventional appraisal requirements |
| Best For | Many first-time buyers | Buyers with stronger financial profiles |
Rather than asking:
"Which loan is better?"
Ask yourself:
What monthly payment am I comfortable with?
How much do I want to put down?
What is my current credit profile?
How long do I expect to own this home?
Is preserving cash after closing important?
What are my long-term financial goals?
Your answers usually make the right loan much clearer.
One of the biggest myths in real estate.
Many qualified buyers purchase homes with significantly less than 20% down, depending on the loan program and their financial situation.
Not necessarily.
While many first-time buyers use FHA financing, eligibility depends on the loan guidelines rather than whether you've owned a home before.
Neither loan is universally better.
The right choice depends on your financial profile and goals.
Imagine two buyers purchasing similar homes.
Buyer A chooses an FHA loan because preserving cash for emergencies is their top priority.
Buyer B qualifies for a Conventional loan with stronger credit and prefers a financing structure that better aligns with their long-term plans.
Both buyers achieve homeownership successfully because they selected the loan that matched their personal goals—not because one loan was objectively better than the other.
Don't compare loan programs based solely on the interest rate.
Ask to compare the complete financial picture, including estimated monthly payment, mortgage insurance, cash needed at closing, and your long-term goals.
I've found that buyers who review multiple financing scenarios before touring homes make more confident decisions and experience fewer surprises during the buying process.
Eligibility and minimum down payment requirements vary by loan program and borrower qualifications. Reviewing your specific scenario with a qualified lender is the best way to determine your options.
In some situations, buyers may refinance into a different loan if it aligns with their financial goals and market conditions. Whether refinancing is beneficial depends on many factors.
It depends. Monthly payments are influenced by the loan amount, interest rate, mortgage insurance, taxes, homeowners insurance, and other factors.
Qualification standards differ between loan programs and depend on your overall financial profile.
Completed Guides
? Guide #1 — Best Houston Suburbs for First-Time Home Buyers
? Guide #2 — Should You Buy New Construction?
? Guide #3 — Best Areas Near Houston for Families Under $400K
? Guide #4 — How Seller Concessions Work in Texas
? Guide #5 — Hidden Costs of Buying a Home in Texas
? Guide #6 — What to Know Before Hiring a Real Estate Broker
? Guide #7 — Houston Property Taxes Explained
Next Recommended Guides
→ Guide #9 — How Much House Can I Afford?
→ Guide #10 — The Complete Houston Relocation Guide
→ Guide #11 — The Home Inspection Guide
Each guide builds on the last, helping you make informed decisions at every stage of your home-buying journey.
Choosing the right mortgage is one of the most important financial decisions you'll make during the home-buying process.
Before you start touring homes, let's compare your financing options, estimate your monthly payment, review your budget, and build a personalized strategy based on your goals.
A Buyer Strategy Session is designed to help you understand your choices before making an offer so you can move forward with confidence.
Jacob Lopez is a Houston real estate broker and mortgage loan originator who helps buyers and sellers throughout the Greater Houston area make informed real estate decisions through education, transparency, and personalized guidance.
The Houston Home Buying & Real Estate Resource Center is an educational library designed to answer the most common questions about buying, selling, and investing in Houston real estate. Each guide builds on the previous one, helping readers become more knowledgeable and confident homeowners.


 Erase note
 You currently have no custom folders