Sign In
Create an account and enjoy all the benefits of HAR.com!
Sign In
Sign in using social account


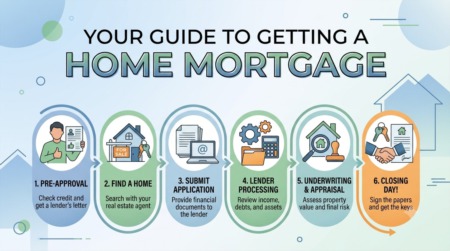
Buying a home is one of the most significant financial milestones in a person's life. While scouting neighborhoods and visiting open houses is undoubtedly the most exciting part, securing the financing is arguably the most critical. For many, the mortgage process feels like an overwhelming black box filled with complex terminology, strict requirements, and endless paperwork.
But it doesn't have to be intimidating. By understanding the standard steps involved, you can navigate the mortgage journey with confidence and ease. Here is your comprehensive, step-by-step roadmap to getting a home mortgage.
Before you even talk to a lender, take a close look at your financial health. Lenders evaluate your creditworthiness, debt-to-income (DTI) ratio, and down payment savings.
Check your credit: Request a copy of your credit report, check for errors, and work on paying down existing credit card balances.
Keep things stable: Avoid opening any new lines of credit, changing jobs, or making large purchases (like financing a new car) that could disrupt your credit profile during this period.
Save for a down payment and closing costs: Remember, you will need money not just for the down payment, but also for fees like the appraisal, loan origination, and title insurance.
A pre-approval is a conditional commitment from a lender stating exactly how much money they are willing to lend you. It involves a pull of your credit score and a preliminary check of your income and assets. Crucially, a pre-approval letter shows home sellers that you are a serious, qualified buyer, giving you a competitive edge when making an offer on a home.
Pro-Tip: Shop Around for Lenders Don't settle for the first quote you receive. Compare interest rates, loan terms, and closing fees across multiple institutions—including national banks, local credit unions, and independent mortgage brokers. Even a 0.25% difference in your interest rate can save you tens of thousands of dollars over the life of a 30-year loan.
With your pre-approval letter in hand and a trusted real estate agent by your side, you can begin shopping. Once you find the perfect house within your budget, submit an offer. If the seller accepts, you will sign a purchase agreement, make an earnest money deposit (which is held in escrow), and officially begin the formal loan application.
Now, you return to your chosen lender to submit the official mortgage application. This step requires a mountain of documentation. Be prepared to provide:
Tax returns and W-2s from the last two years
Recent pay stubs (usually covering 30 days)
Bank and asset statements (checking, savings, retirement accounts)
Verification of other sources of income or debts
The lender will issue a Loan Estimate within three business days of receiving your application, detailing your expected interest rate, monthly payment, and closing costs.
Once your application is in, the behind-the-scenes work begins. A loan processor compiles your file, and an underwriter evaluates the risk of lending to you.
The Appraisal: Simultaneously, the lender will order an independent home appraisal to ensure the home's market value matches the purchase price.
Reviewing the Risk: The underwriter will verify every detail of your financial history before issuing a final decision. They may request "letters of explanation" for certain bank transfers or older credit marks—respond to these quickly to avoid delays.
When the loan is fully approved, you will receive a "Clear to Close." At least three days before your closing date, the lender will send a Closing Disclosure (CD). Compare this document closely with your initial Loan Estimate to ensure there are no unexpected fee changes.
On closing day, you will:
Sign a stack of legal documents (including the mortgage note and deed of trust).
Pay your down payment and closing costs via wire transfer or cashier's check.
Receive the keys to your new home!
While the mortgage process has many moving parts, staying organized and working with an experienced team of professionals makes all the difference. Prepare your finances early, ask plenty of questions, and take it one step at a time. Your dream of homeownership is well within reach!


 Erase note
 You currently have no custom folders