Sign In
Create an account and enjoy all the benefits of HAR.com!
Sign In
Sign in using social account


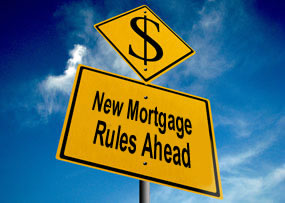
Interested in a different property? The property foreclosure scandal in recent times and awful lending techniques have designed some upgrades in the house loan business. The other mortgage loan procedures, going into effect in 2014, may impair your own capability to get that upcoming home loan.
The reason why the Rules Changed?
These mortgage rule updates happened to be developed to shield customers against careless lending methods that use unique ways in order to offer consumers money they cannot manage to pay back. When their houses are foreclosed on, those people end up getting a black color score on their credit file. The government ultimately ends up paying large sums of money in insurance claims against the poor loan, which gets passed to the tax payers.
The regulations will also change home values. Anytime a property gets sold, it maintains the property values in the community. But whenever a house is foreclosed on mainly because inability to make payments, it causes land values within the encompassing neighborhood to move down.
Who Will Be Influenced by the Updates?
Subsequently for those who are in the marketplace for a new residence, or want to sell a house fast, become aware that the Consumer Financial Protection Bureau (CFPB) rule upgrades affect the qualification needs and also the different kinds of residential loans from which to select. A lot of individuals re-financing or selecting a new home feel the negative impacts of the rule modifications mainly because lenders have started battening down the hatches already. The borrowers that will have the majority of problems are those applying for a big mortgage and those that are self-employed, both of whom will go through a significantly tighter qualification process.
The crappy news is that the updates ensure it more complicated to obtain that mortgage and you may not be eligible for the amount that you would like. The good news is that it will shield your home values and help prevent the financial difficulties caused by a terrible loan. The additional regulations as well safeguard lenders from borrower lawsuits, as long as his or her mortgages fall within the recommended regulations.
Qualifying
1. Lenders, are expected to inquire about evidence of income documentation from you. The “ability to pay” guideline is likely to make it complex to close to impossible for individuals to get a mortgage without having proof of income.
2. For FHA loans, loan companies will not be affording you a mortgage if your debt payments (including the mortgage) are higher than 43% of your very own month-to-month income.
3. If you are acquiring a home without any down payment (interest only loans) – a kind of mortgage commonly accessible throughout the past housing growth – expect the qualification process to be stiff and time intensive. You’ll find that most lenders don’t actually provide these kinds of loans any more unless your loaded, feature substantial financial assets, or applying for a “jumbo mortgage” in an area of Houston in which property values are high.
4. Borrowers who are self-employed are going to be required to show two years worth of income sufficient to cover the payments to be able to qualify.
The brand new regulations will also require that lenders take added steps to accommodate the borrowers’ capability to get caught up before initiating the foreclosure process. This could be done by contacting struggling borrower’s faster, working out a loan modification, or offering a short sale. House owners may have alternatives if their loan provider fails to seek out alternatives to foreclosure, so long as workable possibilities are accessible.
Since these guidelines don’t go into effect until this next year, you are likely to still have the ability to purchase a “creative” mortgage this year. But don’t count on it. You would be more well off getting a loan that you will qualify for, or performing and preserving until you choose.




 Erase note
 You currently have no custom folders